![]() |
| "Pill Hill" - Atlanta, Georgia |
Showing posts with label Market Report. Show all posts
Wednesday, February 1, 2012
Understanding the MOB Business
Friday, July 15, 2011
MOB Atlanta Market Report - Mid Year 2011
Metro Atlanta – Atlanta’s specialty use Medical Office Building (MOB) market, totaling approximately 19.1 million square feet, is not immune to the economic factors adversely affecting other sectors of the commercial real estate industry. With over 3.57 million square feet of vacant space and nearly 120,000 additional square feet available in sublease space, vacancy rates of 18.7 percent are at record levels. There are some 512 multi and single tenant medical office buildings that are generally over 9,500 square feet in ten primary submarkets. Non-primary use medical office buildings including traditional office buildings, business parks and retail space are not included in our analysis. While accommodating some medical uses, these properties do not provide the referral basis and services of a professionally run medical building. This pseudo market could be several million square feet; a fraction of the total amount of vacant retail and primary use office space in Metro Atlanta.
Friday, May 27, 2011
MOB Johnson Ferry Market Report - 1Q2011
The Johnson Ferry medical submarket in Cobb County, Georgia is centrally located around the intersection of Johnson Ferry Road -a primary north/south artery, and State Route 120 that connects east to the City of Roswell and west to the City of Marietta. There are 11 medical office buildings (MOBs) with a total of 243,517 square feet in this suburban submarket of which Woodlawn Commons accounts for 74,032 square feet- 30% of the submarket. One interesting dynamic in this submarket is the marketing of traditional office space which houses a blend of medical and non medical tenants but does compete for medical tenants. This pseudo market accounts for approximately 1.2 million square feet in 131 buildings of which 215,000 square feet are vacant.
Tuesday, May 3, 2011
MOB Woodstock Market Report - 1Q2011
Metro Atlanta - The Woodstock medical submarket is located centrally around the intersection of I-575/Canton Road corridor and Hwy 92 in north Cobb and Cherokee County, Georgia. There are 21 medical office buildings (MOBs) with a total of 537,274 square feet in this suburban submarket – part of the larger Northwest Atlanta submarket with 99 MOBs totaling 3.6 million square feet. The nearest hospitals are Northside Hospital-Cherokee (84 certified beds), approximately 12 miles north and Wellstar Kennestone Hospital (633 certified beds), approximately 12 miles south.
Saturday, April 23, 2011
MOB Decatur Market Report – 1Q2011
Metro Atlanta - The Decatur medical office building (MOB) is a mature submarket located around the Dekalb Medical North Decatur Campus and Decatur Hospital in downtown Decatur. There is approximately 926,836 square feet in 24 buildings—the most recent delivered in 1995. Four of the MOBs are on campus of the two hospitals with the remaining within walking distance. Decatur is a unique pedestrian friendly market that experienced occupancy rates over 90% for the past four years. One interesting note, not unique to this submarket, is the marketing of nontraditional medical buildings to health care providers who do not require the inherent referral basis of a typical MOB.
Monday, February 7, 2011
MOB Atlanta Market Report - Year End 2010
Metro Atlanta - Atlanta’s specialty use Medical Office Building (MOB) market totals approximately 18.8 million square feet. There are some 495 multi and single tenant medical office buildings that are generally over 9,500 square feet in ten primary submarkets. Non-primary use medical office buildings including traditional office buildings, business parks and retail space are not included in our analysis. While accommodating some medical uses these properties do not provide the referral basis and services of a professionally run medical building. This pseudo market, however, could be several million square feet; a fraction of the total amount of vacant retail and primary use office space in Metro Atlanta
Thursday, August 12, 2010
MOB Report Mid Year 2010 Investments Trends
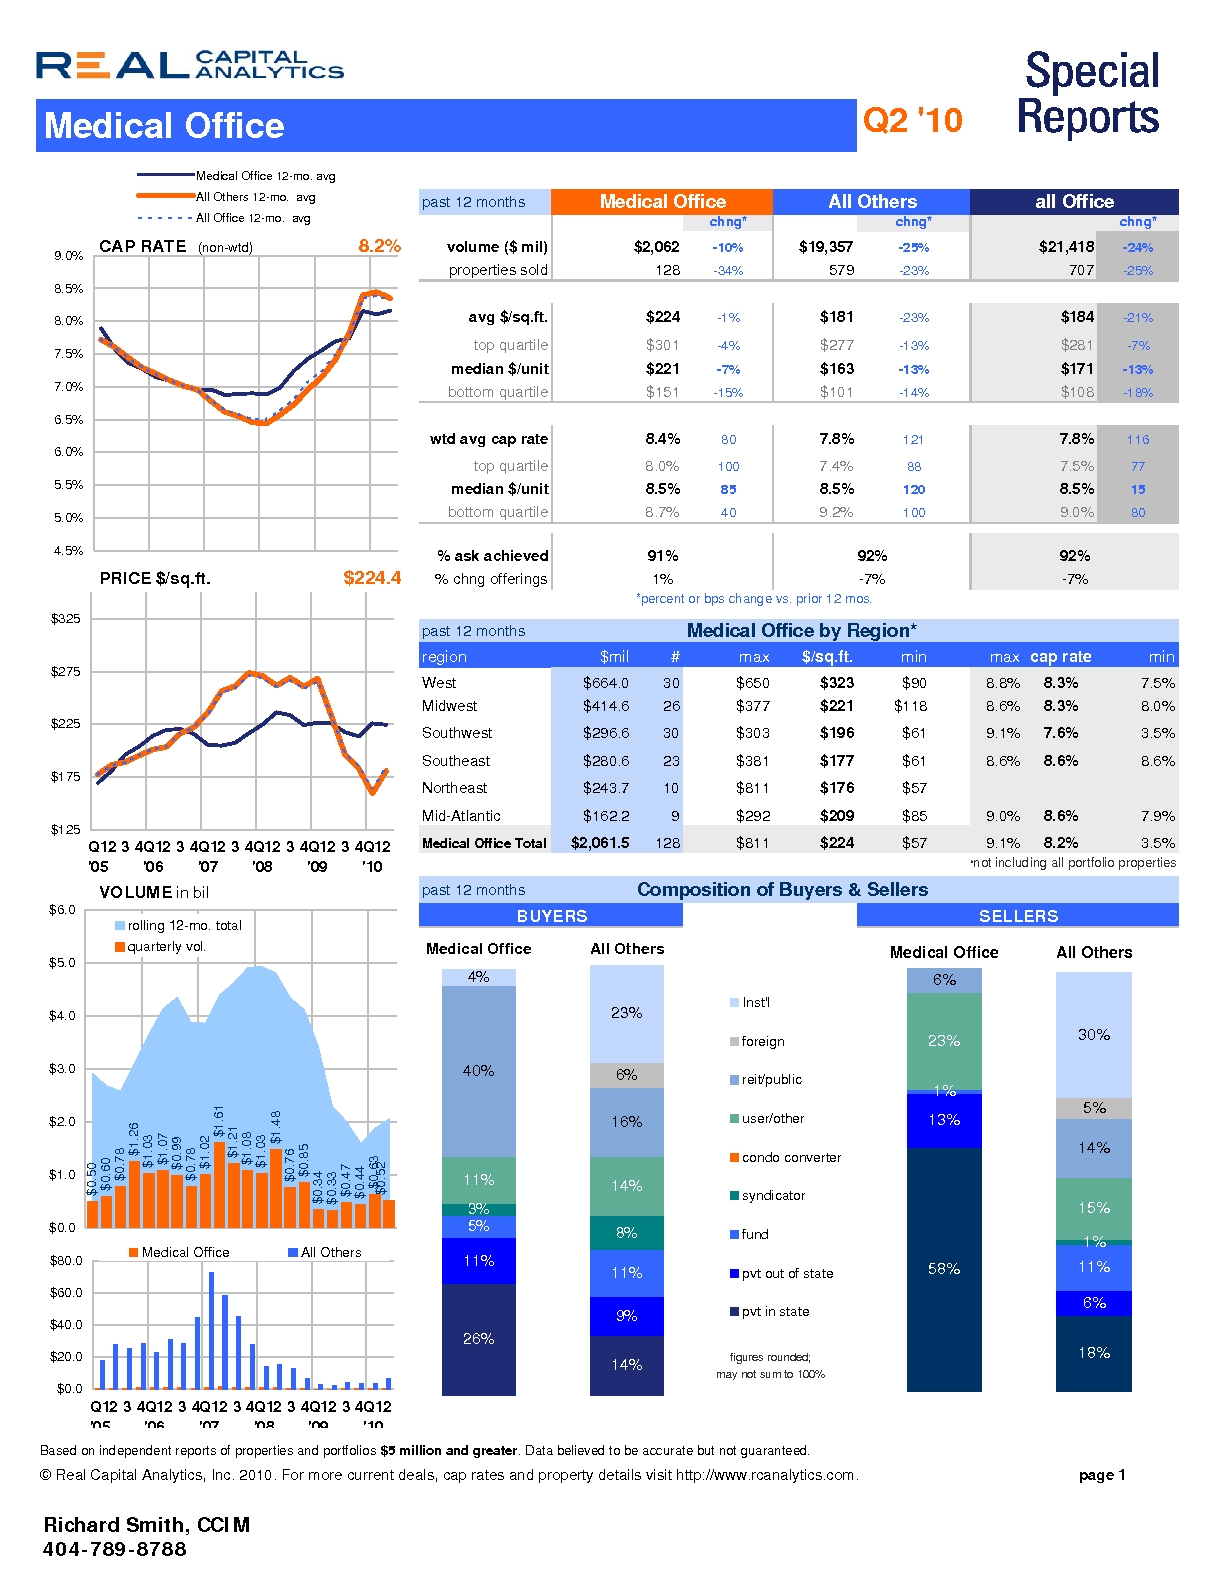
The Mid Year 2010 REAL Capital Report on Medical Office Buildings indicates positive changes for investors of healthcare real estate. The national average price per square foot for Medical Office Buildings (MOB) has risen by $13.00 per square foot to over $224.40 per square foot over year end 2009. However, prices are still well below the historical highs of over $275.00 per square foot in 2007. As comparison the Southeast average is $177.00 per square foot with highest being $323.00 per square foot in the West Region. There is no data recorded for the Atlanta MOB market.
Thursday, July 15, 2010
MOB Atlanta Market Report - Mid Year 2010
Metro Atlanta - Medical office space in Metro Atlanta has been negatively impacted by the recent economic downtown. In real estate terms net absorption is one indicator of the overall health of a market. Overall absorption, the net difference in the amount of space occupied between quarters has been negative in four of the past six quarters. During the 2nd quarter of 2010 the market had a net negative absorption of -174,351 square feet, the largest drop in overall occupied space recorded. Northwest Atlanta and the Central Perimeter markets had the largest net negative losses at -70,572 and -36,155 square feet each. We see this as correction in the market that will start to turn positive by year’s end.
Wednesday, February 17, 2010
MOB Report Year End 2009 Investment Trends
The Fourth Quarter 2009 REAL Capital Report on Medical Office Buildings reveals some interesting trends and backs up what has been reported for the past year. For 2009 verses 2008 Medical Office Building (MOB) sales volume declined by 63%. The average price per square foot was down by -6% however by some measurements up by 9%. This compares to traditional office properties which were down by -71% in sales volume and down by a massive -26% in average prices per square foot. The percent asking price to achieved price was approximately 89% for both type properties.Friday, January 15, 2010
MOB Atlanta Market Report - Year End 2009
Metro Atlanta’s specialty use medical office building market totals approximately 17.457 million square feet in ten primary submarkets. Our research tracks medical office buildings, both multi and single tenant buildings that are generally over 10,000 square feet. Non primary use medical office buildings including traditional office buildings, business parks and retail space are not included in our analysis. While accommodating some medical uses these properties do not provide the referral basis and services of a professional run medical building. Six submarkets account for 80% of the 457 medical office buildings, all areas around large regional medical centers. Four medical office buildings are currently under construction and expected to be completed by the first quarter of 2011 including the Meadows & Ohly development of Gwinnett Medical Center, a 127,000 square foot on campus medical office building.
Friday, November 6, 2009
MOB Fayette/Coweta Market Report– 3Q 2009
The Fayette/Coweta County medical office building (MOB) sub market with 880,000 square feet is located along the Hwy 54 and Hwy 34 corridor form Fayetteville to Coweta Counties in South Atlanta. The largest concentration of space is located around Piedmont Fayette Hospital. The anticipation of the new 9 story, 136 bed hospital in Newnan has created a new emerging market along the Hwy 34 corridor, in Coweta County from Peachtree City west to Newnan (and the older Piedmont Newnan Hospital). Due to the economic downturn the new hospital’s 2010-2011 start date is in question, which has also caused many independent medical office developers to put some plans on hold. Wednesday, October 21, 2009
MOB Northeast Atlanta Market Report - 3Q 2009
For healthcare providers looking to lease space in medical office buildings (MOB), Northeast Atlanta it is a “buyers” market. Vacancies have remained over 20% for the past two years creating an environment where most landlords are prepared to negotiate great deals. In the mid 2000’s vacancy rates where stable around 11%. During this period, as new medical office buildings were completed, tenants expanding and new practices were opened at a pace that absorbed all the new space. However, in 2007 with the delivery of over 300,000 square feet of new medical office buildings and absorption of only 100,000 square feet, vacancy rates spiked by over 7% points. Negative absorption, (a net loss in total square feet occupied) in 2008 and 2009 has pushed vacancy rates to over 22.5% in 3rd quarter 2009. We anticipate this trend to stabilize in 2010 as favorable lease terms and supporting demographics create greater demand for vacant space. Thursday, October 1, 2009
MOB Deliveries at Historical Lows
Metro Atlanta - Medical office building deliveries decline to historical lows. After the building boom of the late 2000’s peaking in 1st quarter 2007 with 553,000 square feet, deliveries are projected to be 100,490 square feet in 4th quarter 2009 and 34,060 square feet in 1st quarter 2010 and 127,000 square feet in 4th quarter 2010. The seven buildings that are scheduled to be completed include:Tuesday, September 29, 2009
MOB Sale Volume Increases in 3Q 2009
Metro Atlanta - Sale of medical office building portfolio doubles total yearly volume in 3Q 2009. The recent sale of Johns Creek I, II and III totaling 72,331 square feet in 8 buildings for $7.7 million pushed total dollar volume for 3Q 2009 to $11.6 million. This represents an increase over the 1Q and 2Q 2009 combined total volume of $5.0 million. The average price per square foot for these MOB sales declined from $172.29 per square foot in 1Q 2009 and $108.57 per square foot in 2Q 2009 to $91.74 per square foot in 3Q 2009. At the time of sale the Johns Creek portfolio was only 45% occupied which lowered the overall price by approximately $2.0 million below asking price. Both building replacement cost and CAP rates at 95% occupancy support the asking price. With current market activity, expect dollar volume to remain strong and sales prices to be in the range of $150.00 to $175.00 per square foot for both smaller investment grade and owner/user MOBs through 4Q 2009.Wednesday, September 2, 2009
MOB Central Perimeter Market Report – Mid Year 2009
The Central Perimeter medical office building market is located at GA 400 and I-285 around the areas three primary hospitals: Northside Hospital, St Joseph’s Hospital of Atlanta and Children’s Health Care of Atlanta at Scottish Rite. The area commonly referred to as Pill Hill has 21 MOBs totaling 2.2 million square feet located both on campus and off campus of the major hospitals. There is approximately 61 spaces available ranging from less then 1,000 SF to over 20,000 SF for a total of 337,835 vacant square feet.
Saturday, July 11, 2009
MOB Atlanta Market Report – Mid Year 2009
The Metro Atlanta medical office building market contains over 15.8 million rentable square feet in 426 properties. Our survey includes medical office properties with over 10,000 rentable square feet. Deliveries steadily increased to the peak of 1.365 million square feet in 2007. In 2008,deliveries fell to 833,000 square feet and 196,000 through 2Q2009. The 198,812 square feet currently under construction in 5 properties is the fewest during the past 10 years. While there are several MOB project start-ups under consideration, the overall market is expected to remain at approximately 16 million square feet through 2010.
Subscribe to:
Posts (Atom)


